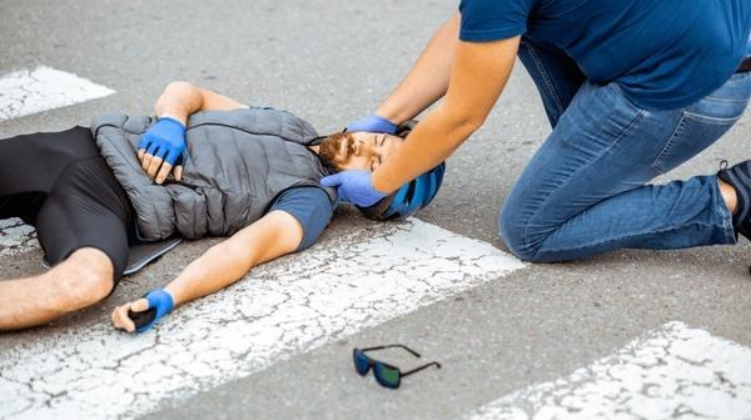
After a car accident, filing an insurance claim can be an important step toward recovering compensation for medical bills, vehicle damage, lost income, and other losses. However, an insurance company may deny a claim or dispute the amount being requested. Understanding common reasons for a denial can help injured drivers recognize potential problems and determine what steps to take next.
Abilene sees traffic on major routes such as Interstate 20, Loop 322, and U.S. 83, as well as busy city streets and intersections. The Abilene Police Department regularly investigates collisions in the area, including serious crashes on Interstate 20 and local roads.
A personal injury attorney in Abilene can review the circumstances surrounding a crash and help determine why an insurance company is disputing a claim. An attorney can examine accident reports, medical records, insurance communications, and other evidence to determine whether the denial is supported by the facts. This can be particularly important when the insurer claims that another factor contributed to the accident or that the requested compensation cannot be established.
1. The Insurer Disputes Who Was at Fault
An insurance company may deny or reduce a claim if it argues that its policyholder was not responsible for causing the accident. Disagreements can arise when drivers provide conflicting accounts, the police report does not clearly establish fault, or there is limited evidence showing what happened.
Photos, witness statements, traffic-camera footage, crash reports, and other available evidence may help establish how the collision occurred. A lawyer can review this evidence and challenge an insurer’s interpretation when appropriate.
2. You Are Accused of Contributing to the Crash
Texas follows a proportionate responsibility system, meaning an injured person may have their recovery reduced according to their percentage of responsibility. Under Texas Civil Practice and Remedies Code § 33.001, a claimant whose responsibility is greater than 50% is generally barred from recovering damages.
An insurer may therefore argue that the injured driver was partly or primarily responsible for the collision. Establishing the actual circumstances of the crash can be important when fault is disputed.
3. The Claim Was Not Supported by Enough Evidence
A claim may face problems if the claimant cannot provide sufficient evidence of the accident, injuries, or financial losses. For example, missing medical records, limited documentation of lost wages, or unclear evidence connecting an injury to the collision can give an insurer grounds to challenge damages.
Keeping copies of medical bills, treatment records, repair estimates, photographs, and other relevant documents can help establish the losses resulting from the crash.
4. The Insurer Questions the Injuries
Insurance companies may dispute whether an injury was caused by the accident, particularly when symptoms appeared after the collision or the claimant had a previous medical condition. Delays in seeking medical treatment can also give an insurer an opportunity to question the severity or cause of an injury.
Prompt medical evaluation and consistent documentation can help establish the connection between the accident and the injuries being claimed.
5. The Policy Does Not Cover the Claim
An insurer may deny a claim because of questions concerning the policy’s coverage, exclusions, limits, or the circumstances under which the accident occurred. Coverage disputes can become complicated when multiple drivers, vehicles, or insurance policies are involved.
Reviewing the applicable policy and determining what coverage is available can help clarify whether the insurer has a valid basis for denying the claim.
6. The Legal Deadline Has Passed
Waiting too long to pursue an accident claim can create another serious problem. Under Texas Civil Practice and Remedies Code § 16.003, a person generally has two years from the date a personal injury claim accrues to bring a lawsuit.
Insurance negotiations do not necessarily eliminate the need to consider the applicable legal deadline. Speaking with an attorney early can help an injured person understand the time limits that may apply and avoid losing the opportunity to pursue a claim.
Key Takeaways
- An insurer may deny a claim because fault is disputed.
- Allegations of shared responsibility can reduce or prevent recovery.
- Insufficient evidence may make injuries and losses difficult to prove.
- Coverage disputes can affect whether compensation is available.
- Delaying action can create statute of limitations problems.
- Legal guidance can help challenge an unreasonable claim denial.